Beyond the Instrument: Understanding the Architecture of Complex Financial Transactions
Complex financial requirements are often approached through the instrument itself: a standby letter of credit, a bank guarantee, a liquidity facility, a digital asset position or another financial mechanism.
Yet the presence of an instrument does not, by itself, create a viable transaction.
In complex international environments, successful execution depends on a much broader architecture: the economic purpose of the transaction, the quality and capacity of the parties involved, the contractual framework, compliance requirements, banking acceptability and the practical sequence through which each stage can be implemented.
Understanding this distinction is fundamental.
The instrument is only one component
Financial instruments have specific functions.
A standby letter of credit, for example, is fundamentally an independent undertaking that may provide assurance of payment when its documentary conditions are satisfied. International practice surrounding standby letters of credit is addressed through established frameworks such as ISP98, while other documentary credits and demand guarantees may operate under different rule sets. ICC Connaissances 2 Go
But identifying an instrument does not answer the broader questions surrounding a transaction.
What is the underlying economic purpose?
Who are the applicant, beneficiary and other relevant counterparties?
What obligation is the instrument intended to support?
Is the proposed instrument appropriate for that purpose?
Will the institutions and counterparties involved accept the proposed structure?
What contractual, regulatory and operational conditions must be satisfied?
These questions transform a discussion about an instrument into a discussion about transaction architecture.
Structure must precede execution
Complex transactions involve interdependent components.
The contractual framework must correspond with the intended financial mechanism. The roles and responsibilities of each participant must be understood. Banking procedures must be compatible with the proposed transaction. Documentation must reflect the actual commercial relationship rather than an assumed process.
The order in which these elements are addressed matters.
Attempting to execute before establishing a coherent structure frequently creates unnecessary friction. Documents circulate between parties without a clearly agreed transaction pathway. Banking terminology may be used inconsistently. Counterparties can have different expectations regarding procedure, timing or responsibilities.
A structured approach begins differently.
It starts by establishing the objective and then works backwards to determine the architecture required to achieve it.
That may involve financial, legal, banking, compliance and operational expertise working within the same overall transaction framework.
Counterparty quality matters as much as transaction design
A technically credible structure still depends upon credible participants.
This is particularly important in cross-border transactions involving significant values, financial instruments, complex corporate structures or digital assets.
Identity, beneficial ownership, source of funds where applicable, business purpose and the nature of the intended transaction can all form part of appropriate due diligence. International AML/CFT standards are themselves based on a risk-based approach: risks should be identified, assessed and understood so that proportionate measures can be applied. GAFI
Higher-risk circumstances may justify enhanced verification, including additional information concerning counterparties, beneficial ownership, source of funds or wealth, and the purpose and intended nature of a transaction. GAFI
For complex transactions, due diligence should therefore not be regarded merely as an administrative stage occurring at the end of a process.
It is part of the architecture itself.
A transaction that cannot withstand appropriate verification is unlikely to become stronger simply because its proposed financial structure appears attractive.
Banking messages are not substitutes for economic substance
Complex financial discussions frequently focus on terminology and messaging: instrument formats, SWIFT messages, readiness communications and proposed banking sequences.
These elements can be important, but they must remain connected to the underlying transaction.
A banking message cannot compensate for an unclear economic purpose, an unsuitable instrument, an unverified counterparty or an incomplete contractual framework.
Similarly, terminology should not be interpreted in isolation. The nature of an instrument, the rules governing it and the obligations it supports must be considered together. ICC guidance, for example, distinguishes standby letters of credit and guarantees while recognising that both can support a wide range of commercial and financial obligations. ICC Académie
The practical question should therefore not simply be:
“Can this instrument be issued?”
It should be:
“Does this instrument form part of a coherent, verifiable and executable transaction?”
That is a substantially different question.
Complex transactions require coordinated expertise
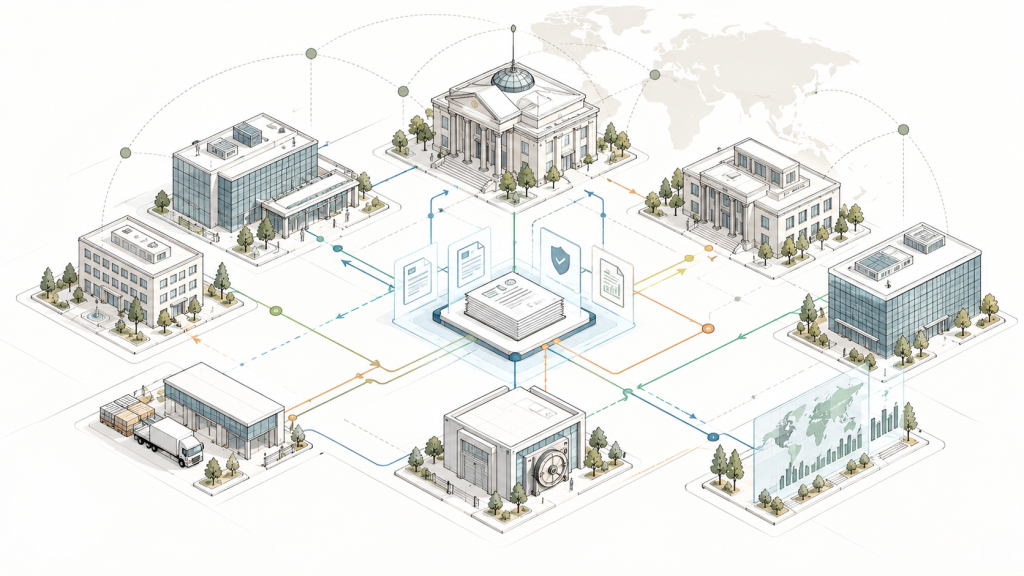
International transactions rarely depend upon a single professional discipline.
Depending on their nature, they may require coordination between:
- banking institutions;
- legal advisers;
- compliance professionals;
- financial specialists;
- corporate counterparties;
- asset owners;
- liquidity or execution counterparties;
- technical specialists;
- and other regulated or specialised professionals.
The objective is not to multiply intermediaries.
It is to identify the expertise genuinely required and establish a clear division of responsibilities.
This becomes particularly important where a transaction crosses jurisdictions. Legal frameworks, compliance expectations, banking practices and commercial conventions may differ, even where the parties believe they are discussing the same transaction.
Effective coordination reduces ambiguity and helps ensure that each specialist is working within the same execution framework.
From financial requirement to solution architecture
This is where the concept of solution architecture becomes relevant.
The starting point is not a predetermined financial product.
It is the requirement.
A structured review can then consider:
Objective — What is the project or transaction seeking to achieve?
Assets and resources — What financial capacity, instruments, assets or contractual rights are genuinely available?
Parties — Who controls them and who has authority to act?
Constraints — What legal, banking, regulatory, timing or jurisdictional limitations exist?
Verification — What information and documentation will counterparties reasonably require?
Architecture — Which combination of professional expertise, counterparties and transaction mechanisms may provide a viable pathway?
Execution — In what sequence should the transaction proceed, and which party is responsible for each stage?
This approach also makes it possible to identify unsuitable structures early, before substantial time and resources are committed.
The FCUBE SOLUTIONS Ltd perspective
FCUBE SOLUTIONS Ltd approaches complex financial requirements from this architectural perspective.
Our role is to understand the requirement, analyse the relevant constraints, help structure an appropriate pathway and coordinate the specialised expertise and professional counterparties required for its implementation.
This distinction is important.
FCUBE SOLUTIONS Ltd does not seek to replace the banks, regulated professionals or specialised counterparties whose respective functions may be required within a transaction.
Instead, the objective is to create clarity between those functions and to establish a coherent framework within which they can interact.
For complex projects, that coordination can be as important as any individual component of the proposed solution.
Beyond the instrument
Financial instruments can play an important role in international transactions.
But their nominal value or technical designation tells only part of the story.
A credible transaction requires economic substance, appropriate counterparties, coherent documentation, due diligence, institutional acceptability and an execution pathway capable of connecting all of those elements.
The most useful question is therefore rarely:
“What instrument is available?”
It is:
“What structure can transform the underlying requirement into a credible pathway towards execution?”
That is where transaction architecture begins.
Important Notice
FCUBE SOLUTIONS Ltd is an international advisory and solution architecture company. It is not a bank, lender, broker, investment firm, financial institution, custodian or issuer/provider of financial instruments. FCUBE SOLUTIONS Ltd does not provide regulated investment or financial advice.
Where a project requires regulated financial, legal, banking or other professional services, these are provided by appropriately authorised independent counterparties and professionals.
Content published in Insights is provided for general informational purposes only and does not constitute an offer, solicitation, investment recommendation or commitment to enter into any transaction.